What overall tax rate do you pay?
Posted on October 2, 2026

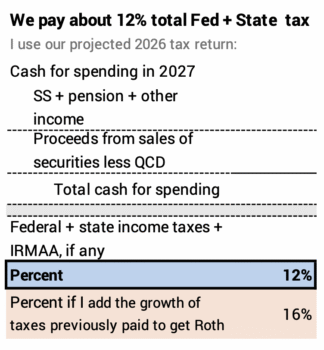
I calculate that Patti and I pay about 12% total tax to get the cash we want for our spending; it’s 16% if I add back the tax I previously paid to get the amount I distribute from Roth – the amount of tax I would pay if I had not previously converted. The bite is less than I thought it would be. I’m guessing you don’t think your overall tax rate is this low. I give you a spreadsheet if you want to do the same calculation.
Details:
The spreadsheet here gives the detail of how I get to 12% total tax on the gross amount of cash we want for our spending. The spreadsheet I used to calculate total federal taxes is in this post.
== Four sources of cash for us ==
Patti and I have four sources of cash: 1) Social Security; 2) a small defined benefit pension that I have; 3) some “other income”, and 4) sales of securities from our portfolio.
Sales of securities from our portfolio are more than twice the sum of first three sources; that’s likely true for you. Sales of securities for our spending are from 1) our Traditional IRAs (RMD less QCD); 2) sales from my Roth from conversions I started in 2018; and 3) sales of securities in our joint brokerage account.
== Two tax bites ==
The tax bite is the sum of 1) taxes on ordinary income and 2) taxes on income taxed at capital gains rates. The amount I sell and distribute from Roth is not taxed. I include IRMAA, if any, to get the total bite.
== Spreadsheet calculates total federal tax ==
I use the tax return spreadsheet from the prior post to calculate our total federal tax; I know where we stand on IRMAA that will be paid in 2027 from our 2025 return filed before last April 15. I separately calculate our state tax.
Conclusion: I calculate that the tax bite is 12% on the gross amount of pre-tax cash for our spending in 2027. It’s 16% if I add back the tax I previously paid on the Roth I distributed. The tax bite is smaller than I thought it was. I give detail on my calculation in this post and give you a spreadsheet if you want to do the same calculation.